Skip to content

The question

What has life taught you about being human?

Originally asked

Krista Tippett, to her guests, On Being

Krista Tippett uses this as a recurring, sometimes-closing On Being question; the wording is intentionally adapted to each guest.

You answer as yourself. Nobody on FLAPSS answers as anybody else.

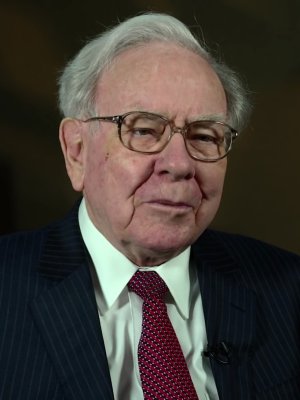
Warren Buffett

Chairman and chief executive of Berkshire Hathaway, 1970–2025

Recorded said elsewhere, not written here
Well, I won't say what I thought about them, particularly related to Bill Gates, but I would say it's astounding to me how human people are. I mean, it, here you had a guy that was a convicted guy, a sensational con man, and the percentage of people that he knocked off. I mean, whether it was, he found their weakness, it might have been sex. It might be power, it might be, whatever it might be.

Becky Quick, CNBC “Squawk Box”, recorded in Omaha; CNBC's own transcript of its own broadcast, 31 March 2026 source ↗

Others on this question

View all 15 →
Ram Dass Spiritual teacher and author
The stroke cut out a lot of my external trips: my sports car and golf and my cello. This [ points to hand ] is just not much use with a cello, and I was—forced inside, and finding myself living in my inside. And that has made me be part of my soul. And that's perceiving my incarnation from here [ points to heart ], rather than from here [ points to head ]. And since this is words, I start from here, go over there.
Recorded Ross Simonini, The Believer, issue 115, by Skype from Hawaii, 20 November 2017 source ↗
Roger Ebert Film critic
When I was a child the mailman came once a day. Now the mail arrives every moment. I used to believe it was preposterous that people could fall in love online. Now I see that all relationships are virtual, even those that take place in person. Whether we use our bodies or a keyboard, it all comes down to two minds crying out from their solitude.
Recorded Roger Ebert's Journal, rogerebert.com, 6 November 2010 source ↗
Paul Kalanithi Neurosurgeon and writer
Everyone succumbs to finitude. I suspect I am not the only one who reaches this pluperfect state. Most ambitions are either achieved or abandoned; either way, they belong to the past. The future, instead of the ladder toward the goals of life, flattens out into a perpetual present. Money, status, all the vanities the preacher of Ecclesiastes described, hold so little interest: a chasing after wind, indeed.
Recorded Stanford Medicine magazine, Spring 2015, 23 February 2015 source ↗
Oliver Sacks Neurologist and writer
My generation is on the way out, and each death I have felt as an abruption, a tearing away of part of myself. There will be no one like us when we are gone, but then there is no one like anyone else, ever. When people die, they cannot be replaced. They leave holes that cannot be filled, for it is the fate — the genetic and neural fate — of every human being to be a unique individual, to find his own path, to live his own life, to die his own death.
Recorded The New York Times, Op-Ed, 19 February 2015 source ↗

More from Warren Buffett

View profile →
Question What part of your job would surprise outsiders because it takes up so much of your time? Craft & work
The extraordinary delegation of authority now existing at Berkshire is the ideal antidote to bureaucracy. In an operating sense, Berkshire is not a giant company but rather a collection of large companies. At headquarters, we have never had a committee nor have we ever required our subsidiaries to submit budgets (though many use them as an important internal tool). We don't have a legal office nor departments that other companies take for granted: human relations, public relations, investor relations, strategy, acquisitions, you name it. We do, of course, have an active audit function; no sense being a damned fool.
Recorded Berkshire Hathaway annual shareholder letter, Berkshire Hathaway Inc., 27 February 2015 source ↗
Question What bad recommendations do people in your field repeat too often? Craft & work
Most investors, of course, have not made the study of business prospects a priority in their lives. If wise, they will conclude that they do not know enough about specific businesses to predict their future earning power. I have good news for these non-professionals: The typical investor doesn't need this skill. ... The goal of the non-professional should not be to pick winners – neither he nor his "helpers" can do that – but should rather be to own a cross-section of businesses that in aggregate are bound to do well. A low-cost S&P 500 index fund will achieve this goal.
Recorded Berkshire Hathaway annual shareholder letter, Berkshire Hathaway Inc., 28 February 2014 source ↗
Question What are you unwilling to optimise? Values & belief
Charlie and I decided long ago that in an investment lifetime it's just too hard to make hundreds of smart decisions. That judgment became ever more compelling as Berkshire's capital mushroomed and the universe of investments that could significantly affect our results shrank dramatically. Therefore, we adopted a strategy that required our being smart - and not too smart at that - only a very few times. Indeed, we'll now settle for one good idea a year. (Charlie says it's my turn.)
Recorded His letter to Berkshire Hathaway shareholders in the 1993 annual report, Berkshire Hathaway Inc., February 1994 source ↗
Question How has a setback or failure set you up for later success? Failure & regret
My first mistake, of course, was in buying control of Berkshire. Though I knew its business - textile manufacturing - to be unpromising, I was enticed to buy because the price looked cheap. Stock purchases of that kind had proved reasonably rewarding in my early years, though by the time Berkshire came along in 1965 I was becoming aware that the strategy was not ideal. If you buy a stock at a sufficiently low price, there will usually be some hiccup in the fortunes of the business that gives you a chance to unload at a decent profit, even though the long-term performance of the business may be terrible. I call this the "cigar butt" approach to investing. A cigar butt found on the street that has only one puff left in it may not offer much of a smoke, but the "bargain purchase" will make that puff all profit. Unless you are a liquidator, that kind of approach to buying businesses is foolish.
Recorded Berkshire Hathaway annual shareholder letter, Berkshire Hathaway Inc., 2 March 1990 source ↗
Question What does everyone in your world seem to agree on that you think is wrong? Values & belief
The strategy we've adopted precludes our following standard diversification dogma. Many pundits would therefore say the strategy must be riskier than that employed by more conventional investors. We disagree. We believe that a policy of portfolio concentration may well decrease risk if it raises, as it should, both the intensity with which an investor thinks about a business and the comfort-level he must feel with its economic characteristics before buying into it.
Recorded His letter to Berkshire Hathaway shareholders in the 1993 annual report, Berkshire Hathaway Inc., February 1994 source ↗
Question Who deserves an apology from you, and for what? Failure & regret
I've mentioned that we strongly prefer to use cash rather than Berkshire stock in acquisitions. A study of the record will tell you why: If you aggregate all of our stock-only mergers (excluding those we did with two affiliated companies, Diversified Retailing and Blue Chip Stamps), you will find that our shareholders are slightly worse off than they would have been had I not done the transactions. Though it hurts me to say it, when I've issued stock, I've cost you money.
Recorded His letter to Berkshire Hathaway shareholders in the 1997 annual report, Berkshire Hathaway Inc., February 1998 source ↗

More on values & belief

Also answered this

Mellody Hobson, Desmond Tutu, Roger Ebert, Rosa Parks, Barack Obama, Ram Dass

Search the directory for somebody in particular.

Explore further

Report this answer